Shriram Finance profit jumps 59% to Rs 3,684 crore as vehicle loans pick up
The lender for trucks, cars, two-wheelers and small shops earned about Rs 40 crore a day from July to September. Here is how a lender makes money.
Picture this: a company that earns about Rs 40 crore of profit every single day, by lending money for trucks, cars, two-wheelers, gold and small businesses. That company is Shriram Finance. On 23 October 2026, it reported a profit of Rs 3,684 crore for July to September 2026. That is 59% more than the Rs 2,314 crore it made in the same three months a year earlier.
How do you get to Rs 40 crore a day? July, August and September have 92 days together. Rs 3,684 crore divided by 92 days is a little over Rs 40 crore a day.
Who is Shriram Finance?
Shriram Finance is the main company of the Shriram Group, which is based in Chennai. The group started in 1974 with chit funds, and later moved into lending and insurance.
Shriram Finance gives loans for many things: trucks and other work vehicles, cars, two-wheelers, small businesses, gold loans and personal loans. Today's company was formed in 2022, when three Shriram companies joined into one.
It is an NBFC, short for non-banking financial company. Think of it as a lender that is not a bank. It lends money like a bank, but it is not set up as one.
The big numbers, in simple words
Here is what changed between July to September 2025 and July to September 2026, as Business Standard reported:
- Profit: up 59%, from Rs 2,314 crore to Rs 3,684 crore.
- Total income: up 16%, from Rs 11,921 crore to Rs 13,802 crore. This is all the money that came in, mostly as interest on loans.
- Net interest income: up 38%, from Rs 6,266.84 crore to Rs 8,661.04 crore. More on this word below.
- Dividend: Rs 6.50 per share. A dividend is a small slice of profit handed to the people who own the company's shares, like a shop owner sharing some of the month's earnings with partners.
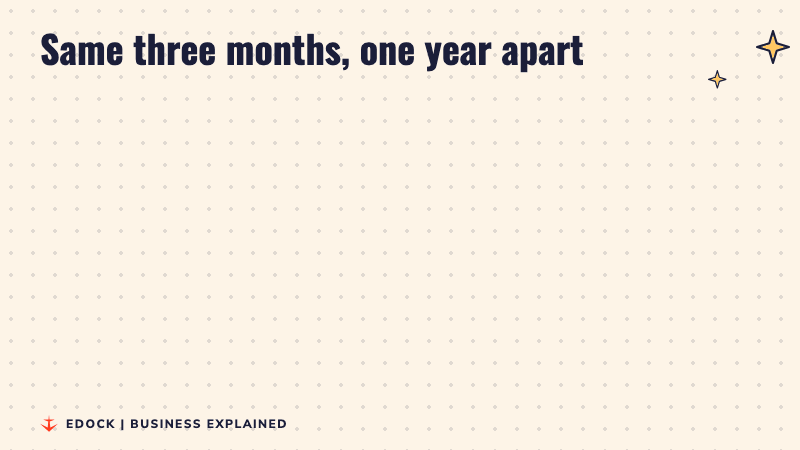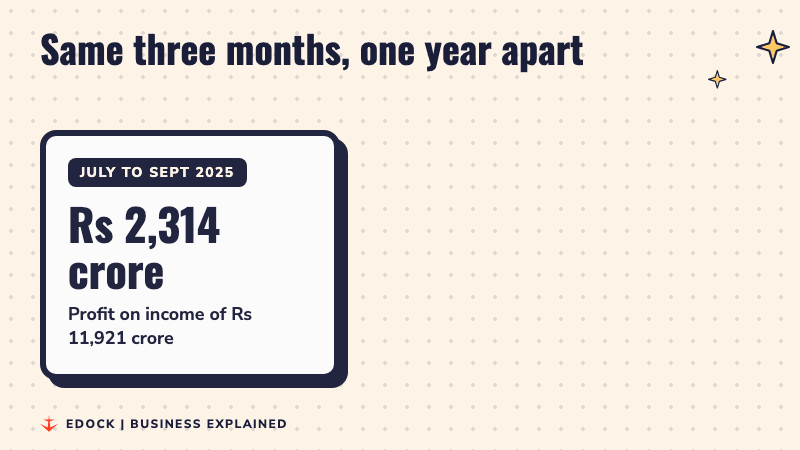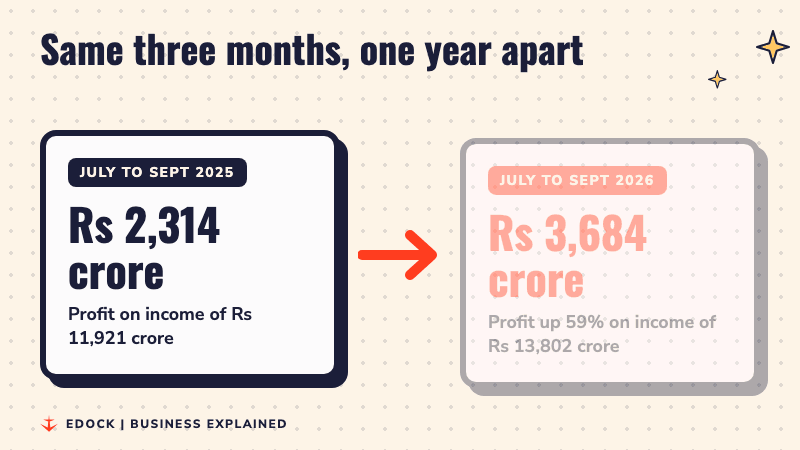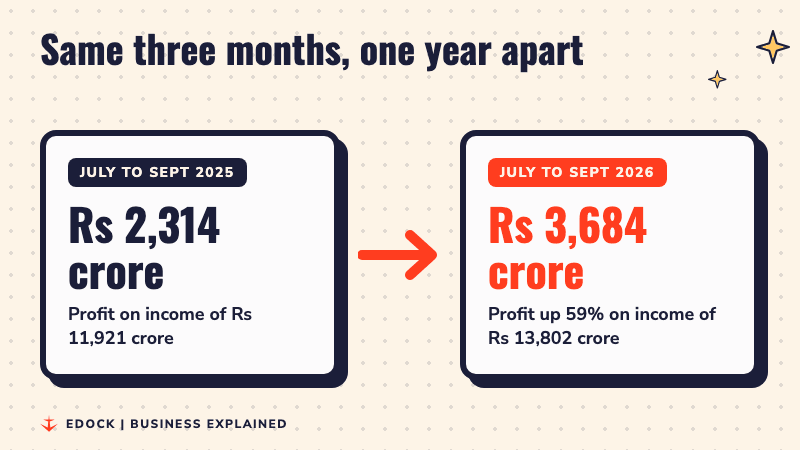
Profit also came in above what experts had guessed. Analysts expected about 35.46 billion rupees of standalone profit (the main company on its own), and Shriram made 36.77 billion rupees, Finimize reported, citing Reuters. That is Rs 3,677 crore.
Why did profit jump so much?
Umesh Revankar, the executive vice-chairman of Shriram Finance, said the rise came mainly from more demand for vehicles after the GST 2.0 tax changes. Those changes came in on 22 September last year, and the vehicle industry was one of the big winners.
Think of it like this. If more people want to buy trucks, cars and scooters, more of them need loans. A lender that is good at vehicle loans gets more customers, the same way a chai stall near a busy bus stop sells more cups when more buses arrive.
The company also gave out more fresh loans. Its new loans in the quarter grew 25.71% to Rs 54,079 crore, according to highlights from its earnings call on 23 October. An earnings call is a meeting where the bosses explain the results to investors and analysts.
How does a lender actually earn money?
A lender works a lot like a chai stall that buys milk in bulk at a low price and sells it by the cup at a higher price. Shriram borrows money at one rate of interest and lends it out at a higher rate. The gap between the two is how it earns.
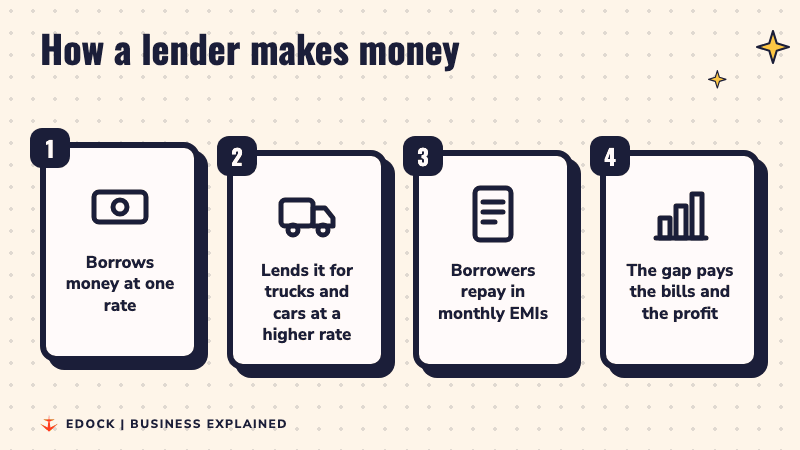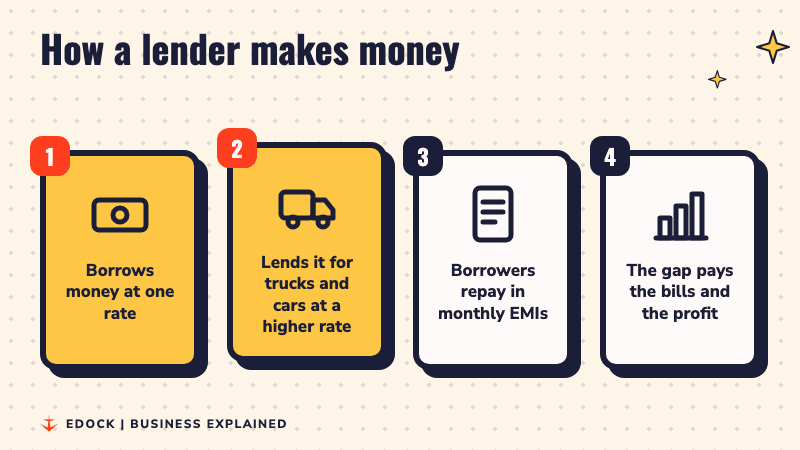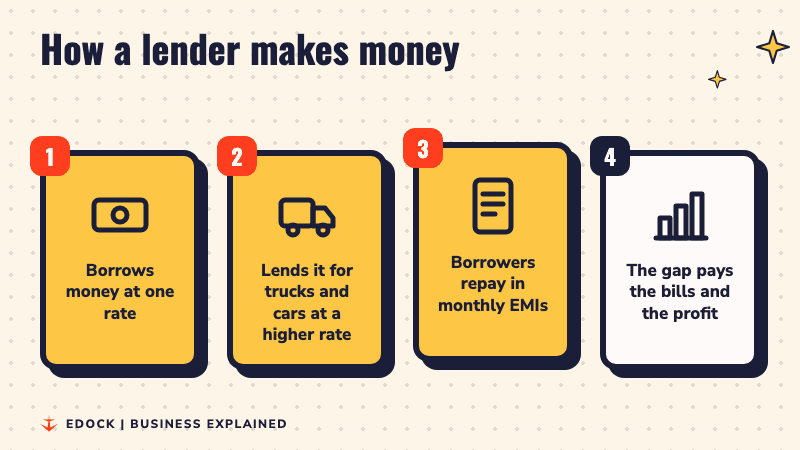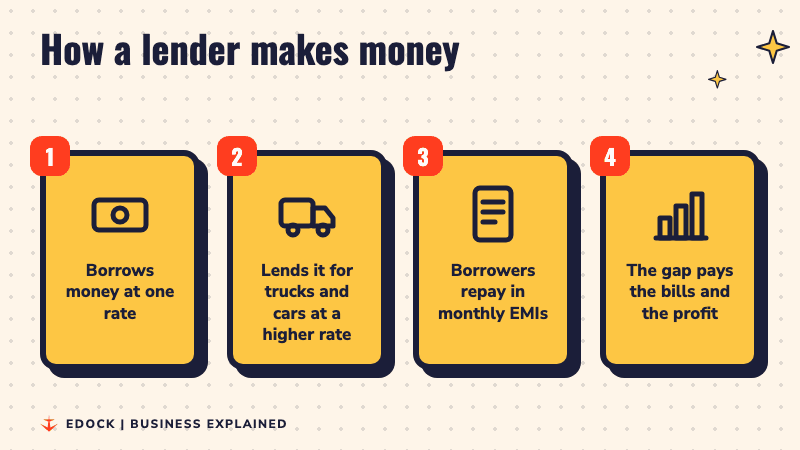
That gap has a name: net interest income. It is the interest Shriram collects from borrowers minus the interest it pays to the people it borrowed from. This rose 38% to Rs 8,661.04 crore.
Another word is net interest margin, which shows that gap as a percentage of the loans. Shriram's margin rose to 9.52% from 8.19% a year ago, the call highlights say, helped by fresh capital and cheaper borrowing. Mr Revankar said this margin is higher than usual for now and should come down to about 9% in the medium term.
What is AUM, and how big is it?
AUM stands for assets under management. For a lender, it means all the money it has lent out that is still to come back. Imagine you lent pocket money to ten friends. The total they still owe you is your AUM.
Shriram's AUM grew 17% in one year, to about Rs 3.29 lakh crore on 30 September 2026, Business Standard reported. It was about Rs 2.81 lakh crore in September 2025 and about Rs 3.14 lakh crore in June 2026.
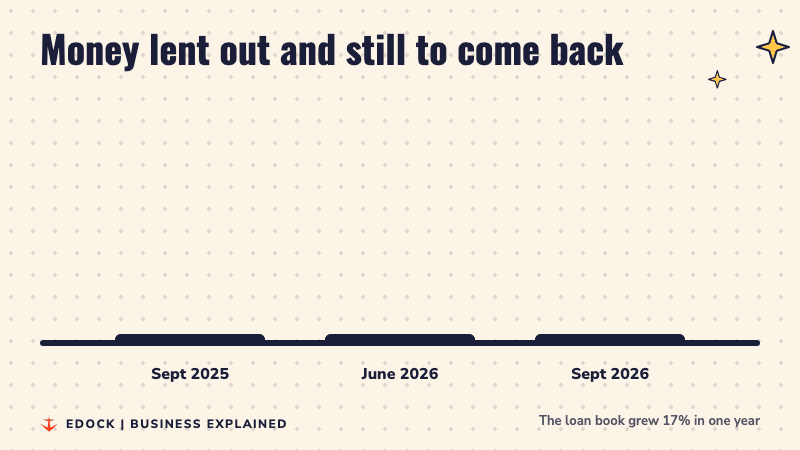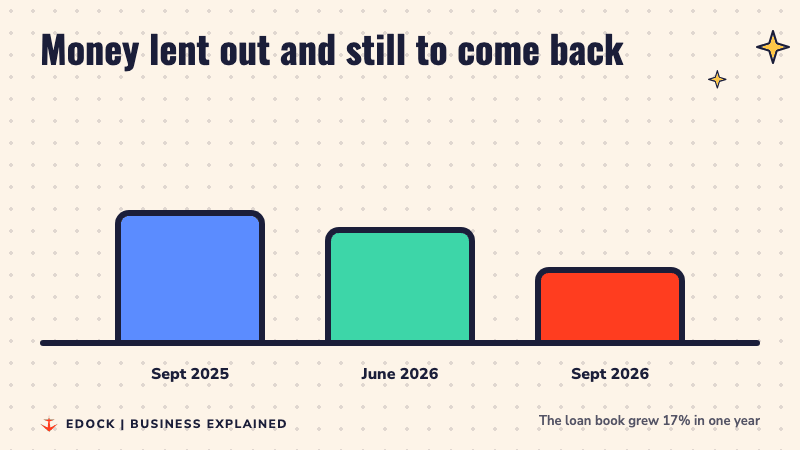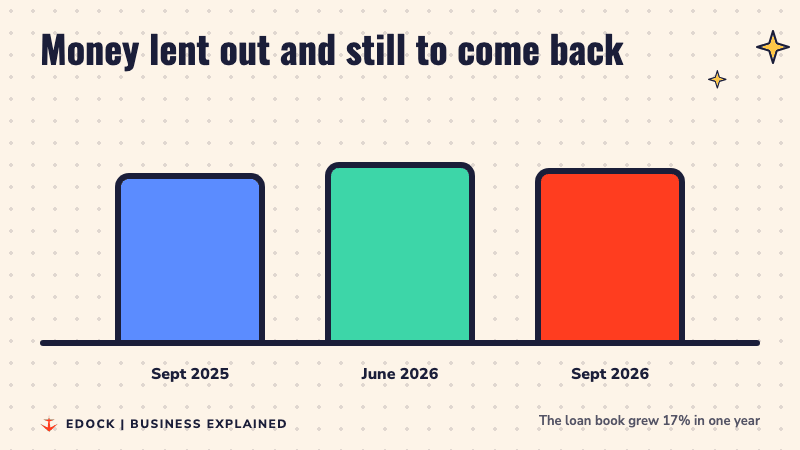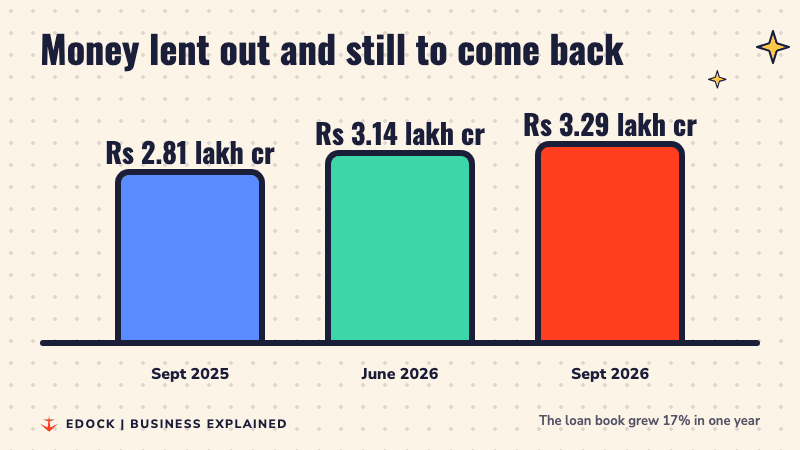
The worry: some gold loans are paid late
Not every number went up in a good way. A lender worries about bad loans: loans where the borrower has stopped paying on time. For a lender like Shriram, a loan more than 90 days overdue is called a Stage 3 loan.
In Shriram's gold loans, Stage 3 loans rose to 3.12% in July to September 2026, from 2.57% in the quarter before and 2.28% a year earlier, Deccan Chronicle reported. Its gold loan book is about Rs 8,974 crore. A gold loan is when you hand over gold jewellery and get cash in return, then pay it back to get the jewellery back.
Mr Revankar explained on the call that Shriram started asking gold loan customers to pay in monthly instalments (EMIs), while many were used to paying everything back in one go at the end. That change led to late payments. He also said gold loans carry no credit cost (money lost on loans that are never repaid), because the company can sell the gold if it has to.
Across all its loans, Stage 3 loans were 4.65%. The share price still fell about 4% after the results, Finimize reported, as investors focused on the gold loan numbers.
What comes next?
Shriram lowered its growth target for the full year. It now expects its loan book to grow 15% to 17% this year, down from 18% earlier, the call highlights show. The reasons given were a weak monsoon and the crisis in West Asia. The company also said loans to small businesses (MSMEs) jumped to almost Rs 10,000 crore in the quarter, from about Rs 6,000 crore earlier, as it expanded across India.
Here is a short video from NDTV Profit on the results:
Why this matters to you
Lenders like Shriram Finance sit behind a lot of everyday India: the truck carrying vegetables to your city, the tempo outside a small shop, maybe even your first scooter. A bigger loan book means more people borrowed from Shriram to buy vehicles and run small businesses.
The lesson is simple. A lender earns from the gap between what it pays to borrow and what it charges to lend. It does well when people repay on time, and it gets nervous when they do not.
Sources
- Business Standard: Shriram Finance Q2 profit jumps 59% to Rs 3,684 crore on auto demand growth
- GuruFocus: Shriram Finance Q2 2027 earnings call highlights
- Deccan Chronicle: Shriram Finance reports rise in bad gold loans in Q2FY27
- Finimize: Shriram Finance beat profit forecasts, but its stock slipped
- Wikipedia: Shriram Group
- Cover photo: Eicher multi-axle lorry near Musiri, Tamil Nadu, by SnapMeUp, CC BY-SA 4.0

You may republish this story under CC BY 4.0: credit Pranav Sharma and link to this page.