IDFC First Bank's profit nearly triples to Rs 1,045 crore in July to September
Version 1 of 1 saved 25 Oct 2026, 8:47 am IST · Chain line 228
As it was first published
IDFC First Bank's profit nearly triples to Rs 1,045 crore in July to September
Lower provisions and a 21% rise in interest income lifted the bank's quarterly profit. Here is how a bank earns, in chai stall terms.
A year ago, IDFC First Bank made a profit of about Rs 352 crore in three months. This year, in the same three months, it made nearly three times that. On Saturday, 24 October 2026, the bank said its net profit jumped 196.5% to Rs 1,045 crore for July to September 2026.
That is a big jump. So what changed? The short answer: the bank earned more from its loans, and it had to keep less money aside for loans that might go bad. Here is the whole story in simple words.
First, the numbers
Banks and companies in India split their year into four parts called quarters. July to September is the second quarter, written as Q2. The bank's year runs from April 2026 to March 2027, so this is "Q2 FY27".
Here is what the bank reported, as per Moneycontrol's report on the results:
- Profit after tax: Rs 1,044.6 crore, up from Rs 352.3 crore a year earlier. Most outlets round this to Rs 1,045 crore.
- Net interest income (NII): Rs 6,184.5 crore, up from Rs 5,112.6 crore. That is a rise of about 21%.
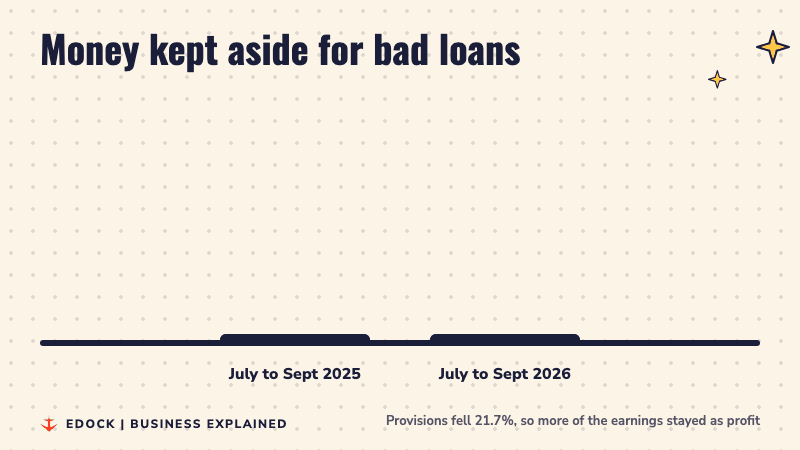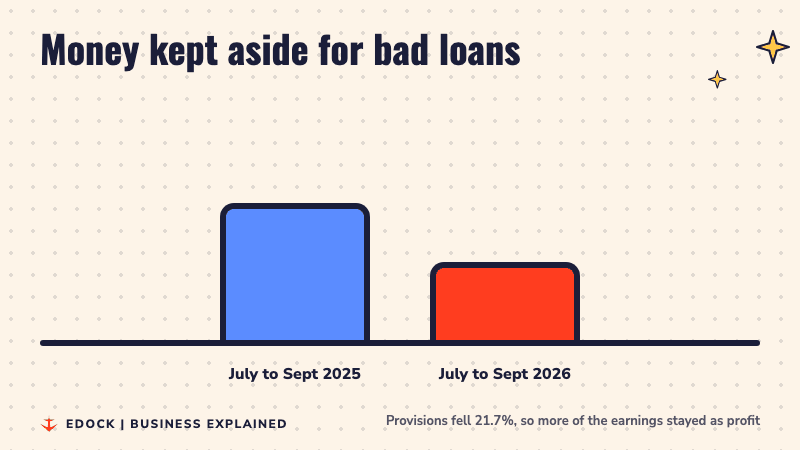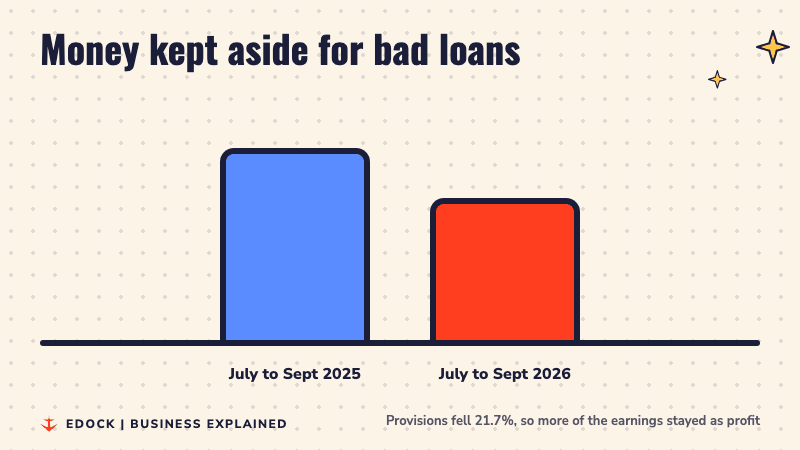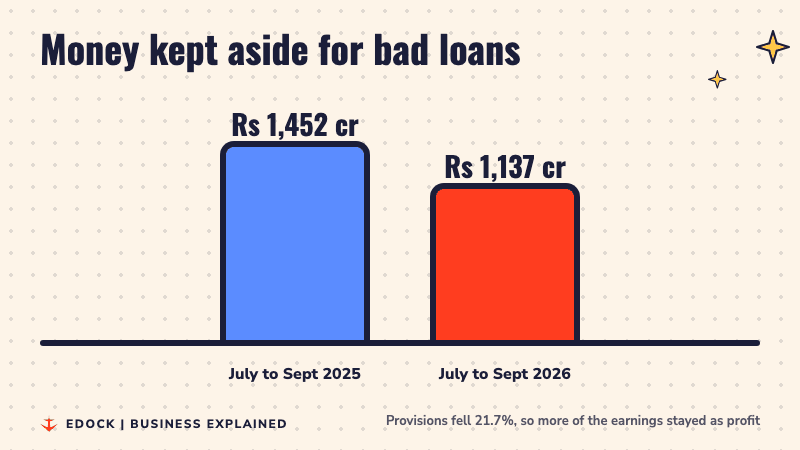
- Money kept aside for bad loans (provisions): Rs 1,137 crore, down from Rs 1,451.8 crore.
"Year on year" simply means comparing with the same quarter last year. It is like comparing your Class 10 marks in the half-yearly exam with your Class 9 half-yearly marks, not with last month's test.
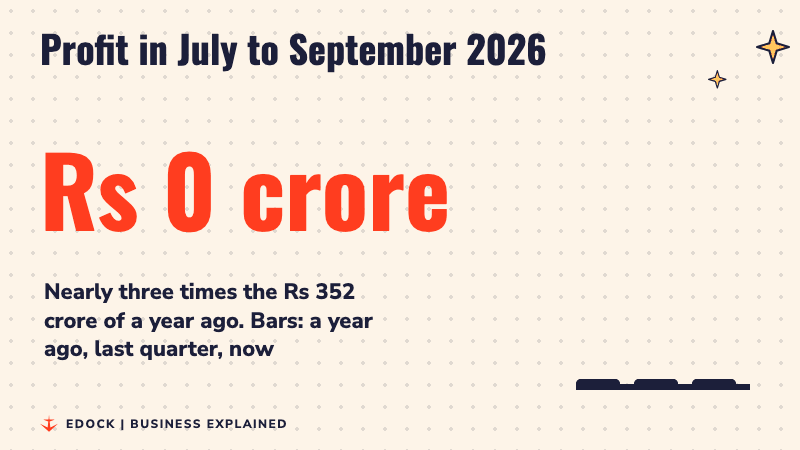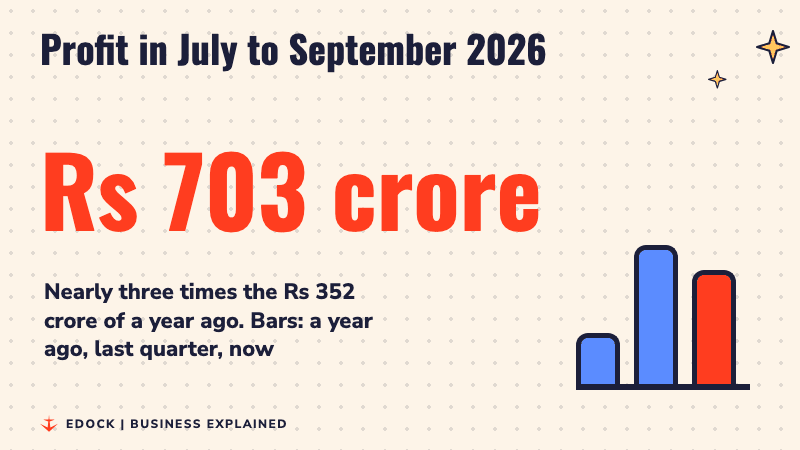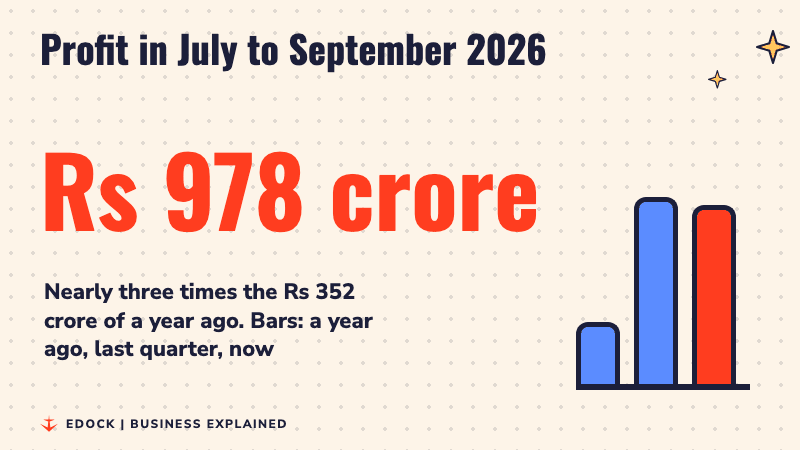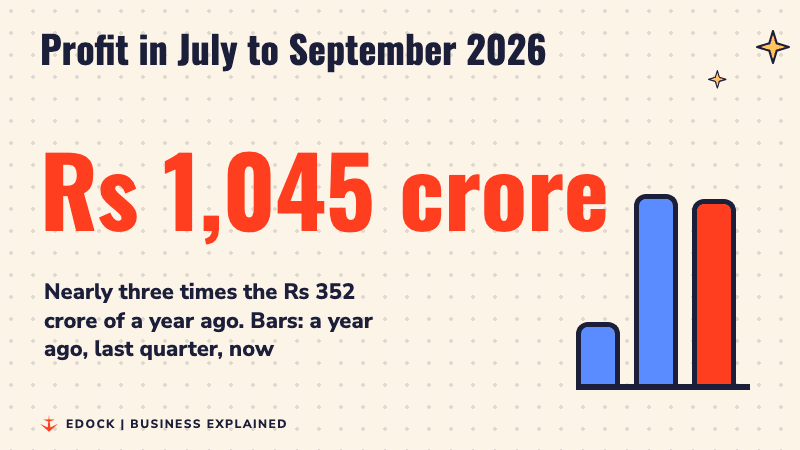
How does a bank make money?
Think of a chai stall. The owner buys milk, tea leaves and sugar. Then the stall sells each cup for more than it cost to make. The gap between the selling price and the cost is what the stall earns.
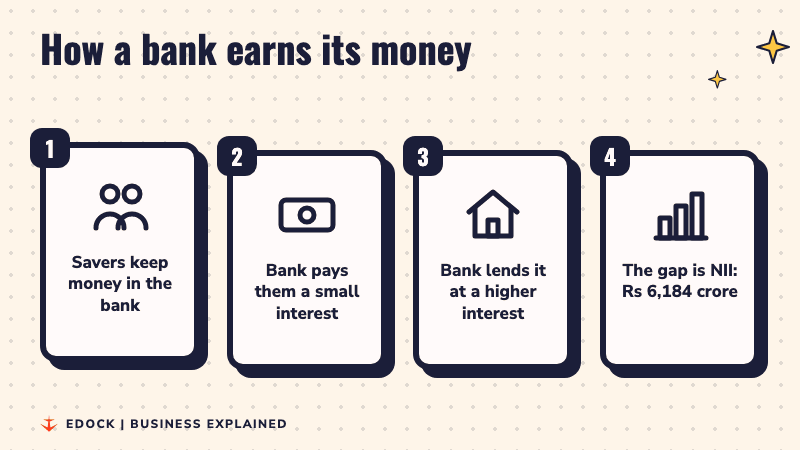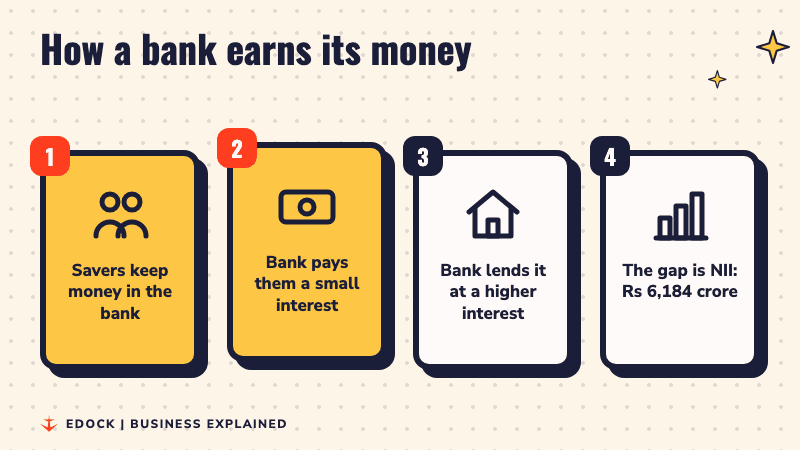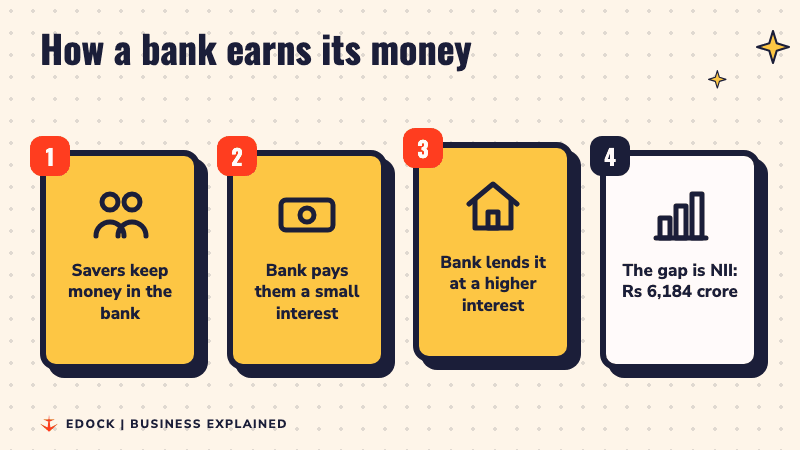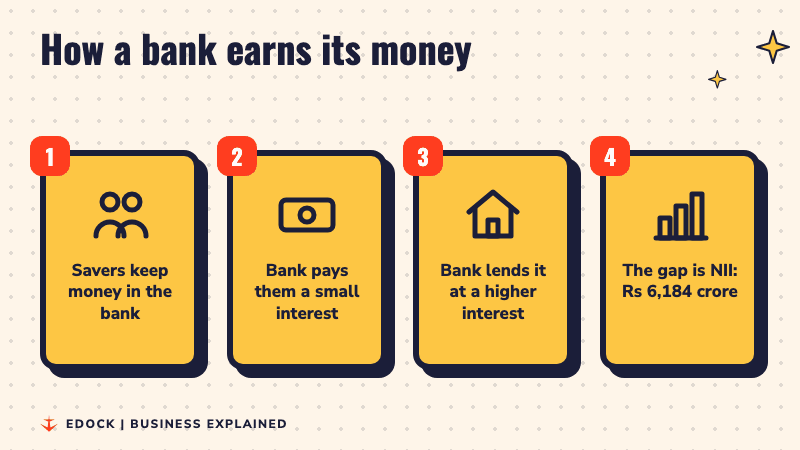
A bank works in a similar way. Its "milk" is money. People keep their savings in the bank, and the bank pays them a small interest for it. Then the bank lends that money to others, for homes, bikes, shops or businesses, at a higher interest. The gap between the interest it earns and the interest it pays is called net interest income, or NII.
For IDFC First Bank, this gap was Rs 6,184 crore in the quarter. That is the main engine of the bank. The bank also earns fees for its services. Its fee and other income grew 24.5% from a year ago, according to The Times of India.
Why was last year's profit so small?
Here comes the word "provisions". When a bank lends money, a few borrowers may stop paying back. A careful bank does not wait to be surprised. It keeps some money aside in advance to cover such losses. That money is called a provision.
Picture this: you lend Rs 500 from your pocket money to five friends. You know one of them often forgets to return money. So you mentally write off Rs 100 in advance. That Rs 100 is your "provision". It is money you cannot spend, even if the friend pays later.
A year ago, IDFC First Bank kept Rs 1,452 crore aside like this in one quarter. This year it kept Rs 1,137 crore aside. The Financial Express reports that provisions fell 21.7% from a year ago. The Hindu says the profit jump was aided by lower provisions and better asset quality. When less money is locked away for bad loans, more of what the bank earns shows up as profit.
Are fewer people failing to repay?
It looks that way from the numbers. A loan where the borrower has stopped paying back is called a non-performing asset, or NPA. Think of it as the friend who has gone quiet about your Rs 100.
The bank's gross NPA fell to 1.32% of its loans, from 1.86% a year ago, as per The Times of India. Net NPA, which is what is left after the money already set aside, fell to 0.40% from 0.53%. In simple words: out of every Rs 100 it has lent, about Rs 1.32 is stuck right now, compared with Rs 1.86 a year ago.
Money from Indians living abroad
One more interesting detail. In the quarter, the bank collected Rs 34,390 crore, or about $3.6 billion, through a type of deposit called FCNR(B). These are deposits kept in foreign currency, like US dollars, by Indians who live outside India.
The surprising part: the bank has no branch or office outside India. It did this through its digital channels. As quoted by The Hindu, managing director and CEO V. Vaidyanathan said these deposits cost the bank about 1% less than raising similar deposits inside India. He added, "Overall, Q2 FY27 was an excellent quarter, and we hope to sustain this momentum."
The bank also got its first international rating, BBB- from S&P Global Ratings. A rating is like a report card on how safe it is to lend to someone. The Financial Express calls BBB- an "investment grade" rating, which in simple words means a borrower seen as safe enough to lend to.
Is everything rising?
Not quite. Compared with the quarter just before (April to June 2026), profit actually dipped a little. The Financial Express says profit fell 2.8% quarter on quarter. In April to June, the bank had earned about Rs 1,075 crore, so the first half of the year added up to Rs 2,120 crore.
So the big jump is mainly against a weak quarter last year, not against last quarter. That matters. One good over in cricket is nice, but fans look at the whole innings.
The bank is also growing fast. Total deposits rose 25.9% to Rs 3,48,583 crore, and loans rose 30.1% to Rs 3,46,913 crore, as per The Hindu. Its total income for the quarter was Rs 14,218 crore, up from Rs 11,828 crore, Rediff reports, quoting the bank's filing.
A new chairperson, too
In a separate filing, the bank said its board approved S. Ganesh Kumar as part-time non-executive chairperson from 10 May 2027, as per Moneycontrol. He will take over from Sanjeeb Chaudhuri.
Why should a young reader care?
If you have a savings account, a debit card or plan to take an education loan one day, you are part of this machine. Your savings are the "milk" a bank uses to lend. How well a bank picks its borrowers decides how much it must keep aside, and that decides its profit. This quarter's result is a simple lesson in that: lend carefully, and fewer rupees get stuck.
This post explains the results. It is not advice to buy or sell any share.
Sources
- The Hindu: IDFC First Bank Q2 PAT rises 197% to Rs 1,045 crore on lower provisions
- Moneycontrol: IDFC First Bank Q2 net profit jumps to Rs 1,044.6 crore
- The Times of India: IDFC First Bank Q2 profit nearly triples to Rs 1,045 crore
- The Financial Express: IDFC First Bank Q2 results
- Rediff Money: IDFC First Bank Q2 profit jumps nearly 3x
- Cover photo: IDFC First Bank Waghawadi Bhavnagar Branch, by IDFC First Bank Photos, CC BY-SA 2.0
