HDFC, ICICI and Axis Bank all grew profit on the same day, at very different speeds
Axis Bank's profit rose 38%, ICICI Bank's 20% and HDFC Bank's 4.7%. Here is what NII, provisions and NIM mean, in plain words.
Picture three cricket teams playing on the same Saturday. All three win. But one wins by a few runs, one wins comfortably, and one wins by a mile. That is roughly what happened when India's three biggest private banks shared their report cards on the same day.
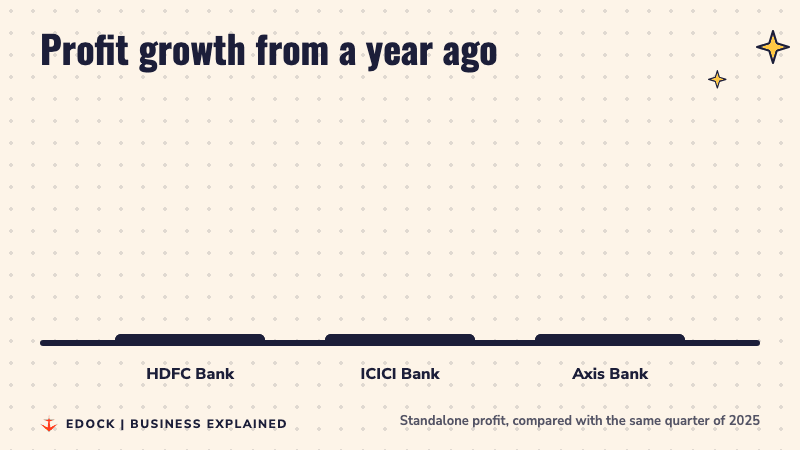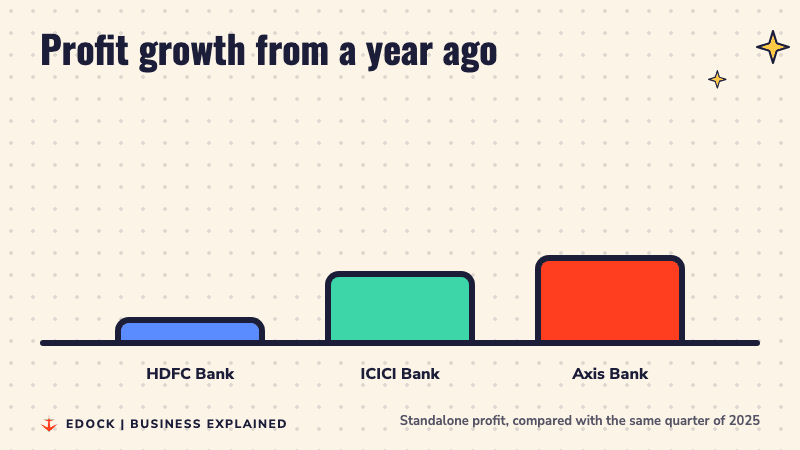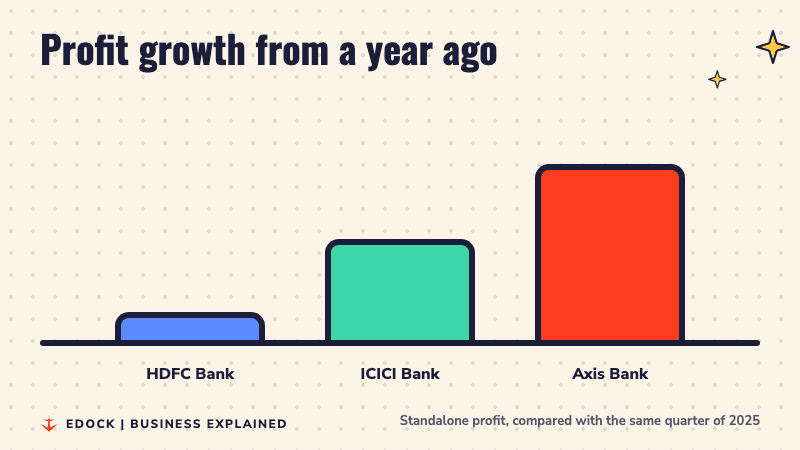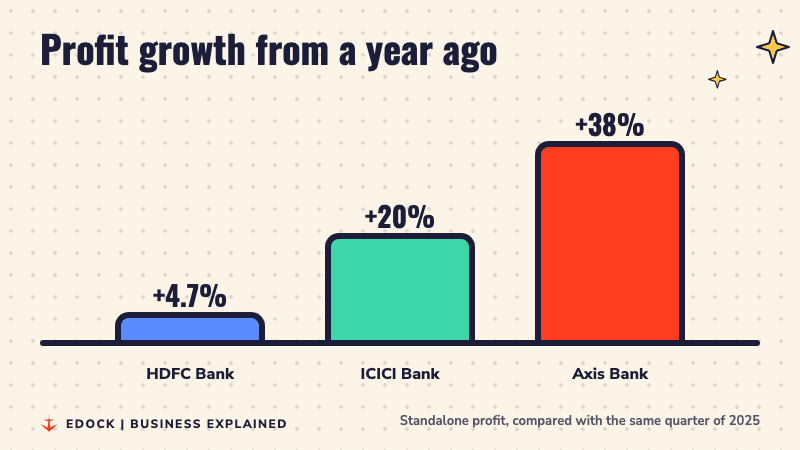
On Saturday, 17 October 2026, HDFC Bank, ICICI Bank and Axis Bank posted their results for July to September 2026. Bankers call this period Q2 FY27, the second quarter (three months) of the financial year that ends in March 2027. All three made more profit than a year ago. Yet the growth was very different: HDFC Bank's profit rose 4.7%, ICICI Bank's rose 20% and Axis Bank's jumped 38%.
To see why, you only need four words: profit, NII, provisions and NIM. Let us learn them one by one.
How does a bank even make money?
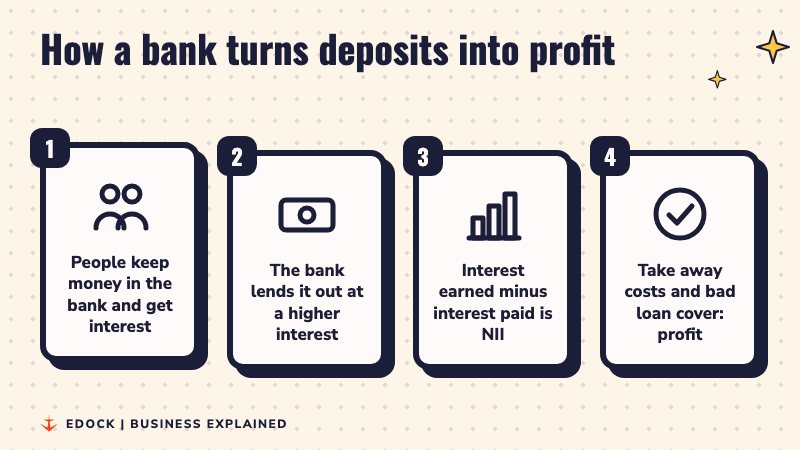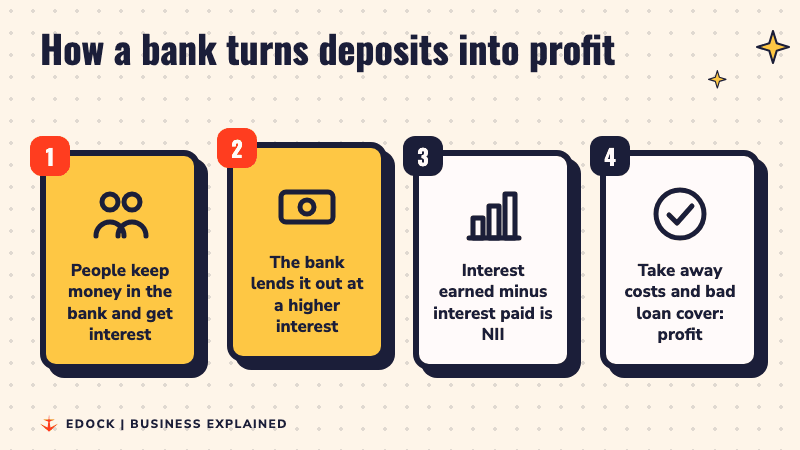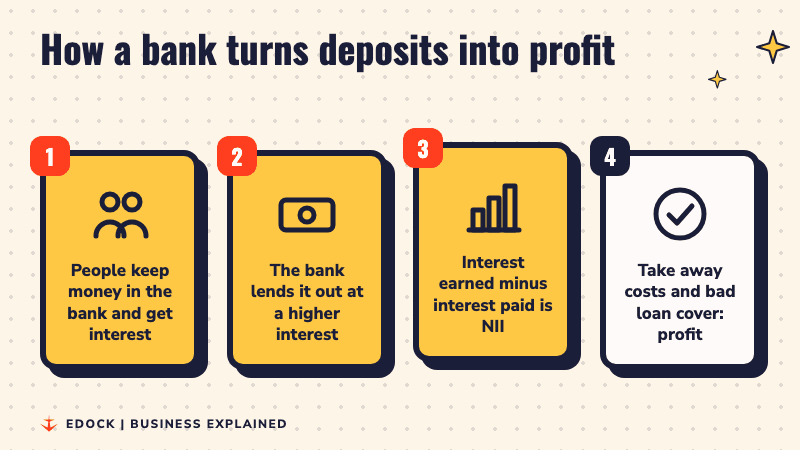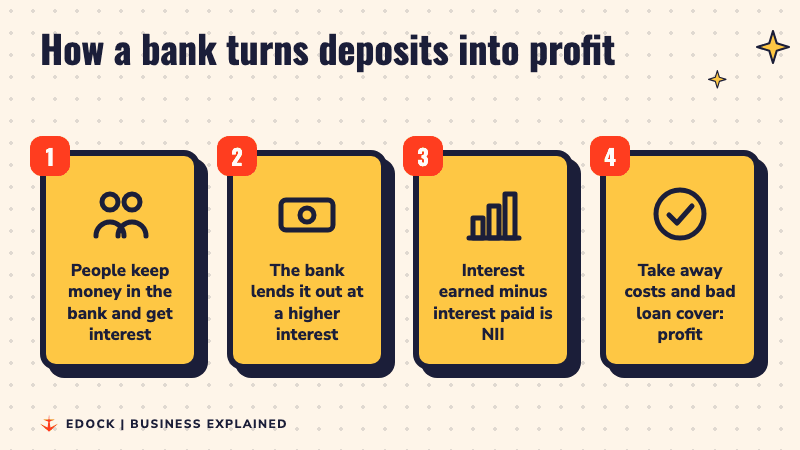
Think of a bank as a big chai stall that sells money instead of tea. People keep their savings in the bank. The bank pays them a little interest for it. Then the bank lends that money to people buying homes, bikes or phones, and to companies building factories. It charges them a higher interest.
The gap between the two is the bank's main income. It has a name: net interest income, or NII. In simple words, NII is the interest a bank earns minus the interest it pays. Business Standard defines it exactly like that.
From NII, the bank still has to pay salaries, rent and computer bills. It also keeps some money aside for loans that may never come back. That safety money is called a provision. Imagine lending your friend Rs 100 and quietly keeping Rs 10 aside, just in case he forgets to pay you back. Whatever is left after all this, and after tax, is the profit.
HDFC Bank: the biggest, but the slowest this time
HDFC Bank, the largest private bank in India, earned a profit of Rs 19,510 crore in the quarter. That is the biggest number of the three. Its NII grew 9.7% to Rs 34,620 crore.
So why did profit grow only 4.7%? Business Standard explains that its "other income" fell 3.6% to Rs 13,830 crore. A big reason was trading gains from government bonds, which dropped to Rs 780 crore from Rs 2,390 crore a year earlier. At the same time, running costs rose to Rs 18,970 crore from Rs 17,980 crore, and the bank set aside Rs 3,570 crore as provisions.
Its bad loans actually improved. The share of loans that have stopped being repaid, called gross NPA, fell to 1.11% from 1.24% a year ago. CEO Sashidhar Jagdishan told reporters that "the margin trajectory should turn upwards from the next quarter onwards", Business Standard reported.
New captain coming in at HDFC Bank
The same day also brought news about who runs the bank. Anup Bagchi, a long-time ICICI Group leader, will take over as MD and CEO on 27 October, The Economic Times reported. He replaces Sashidhar Jagdishan.
Deputy managing director Kaizad Bharucha has asked to step down on 31 December 2026, after more than three decades with the bank. HDFC Bank's board accepted his request on 17 October and will send it to the Reserve Bank of India (RBI) for approval, according to The Economic Times. The bank credited him with building its system for checking who gets a loan.
ICICI Bank: strong profit, thinner margin
ICICI Bank's profit rose 20% to Rs 14,843 crore, up from Rs 12,359 crore a year earlier, The Economic Times reported. This is the "standalone" number, which counts only the bank itself. If you add its group companies too, the "consolidated" profit was Rs 16,333 crore, up 22.3%. This post uses the standalone number so all three banks are compared the same way.
ICICI's NII grew 17.7% to Rs 25,339 crore. Its provisions fell 6.9% from a year earlier, to well under Rs 1,000 crore, and its share of bad loans also improved.
But here is the catch. Its net interest margin, or NIM, slipped to 4.18% from 4.36% in the April to June quarter. NIM tells you how much a bank earns on each Rs 100 it lends and invests, after paying interest. Think of a lemonade stall. If each glass earns you Rs 4.36 extra, and now it earns Rs 4.18 extra, you are still making money, just a little less on every glass.
The dollar deposits squeezing margins
Why did ICICI's margin shrink? Executive director Sandeep Batra linked it to a big pile of deposits called FCNR-B. These are deposits in foreign currencies, like US dollars, from Indians who live abroad. ICICI collected about $18 billion of them under a special RBI window, Mint reported.
These deposits cost the bank about 6.5% once interest and the cost of protecting against rupee swings are added. That is costly money. Batra said margins may dip again in October to December, before they start to move up.
Axis Bank: the fastest grower
Axis Bank made a profit of Rs 7,003 crore, up from Rs 5,090 crore a year ago, Business Standard reported, using a Reuters report. Its NII rose 11.8% to Rs 15,371 crore.
The real secret behind the 38% jump was provisions. Axis set aside only Rs 1,694 crore for bad loans, 52.2% less than a year ago. Less money kept aside means more money left as profit. It is like a samosa seller who spent less on spoiled samosas this month, so more cash stayed in the box.
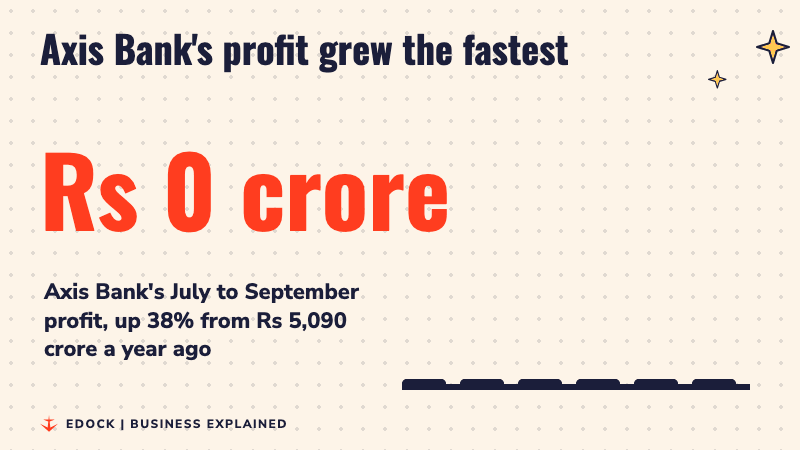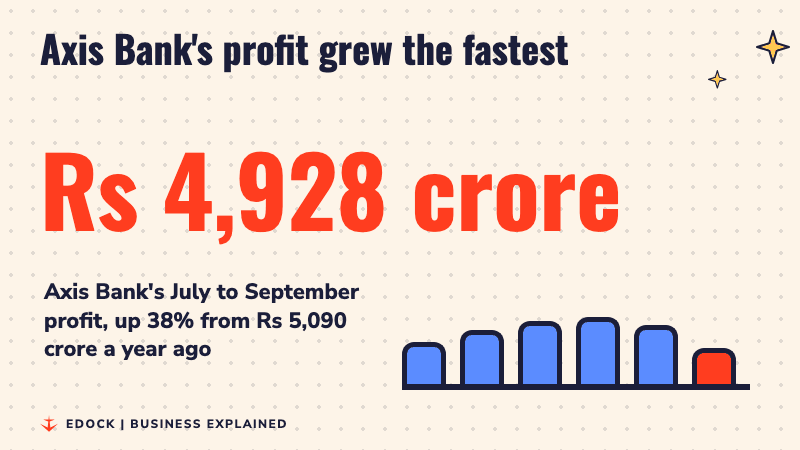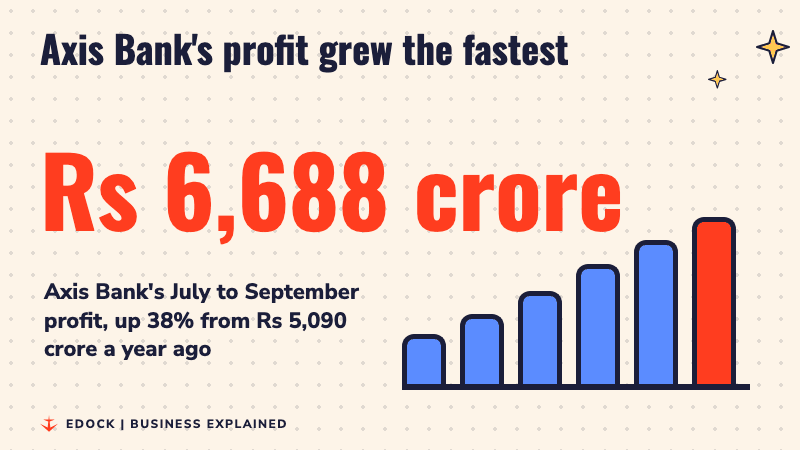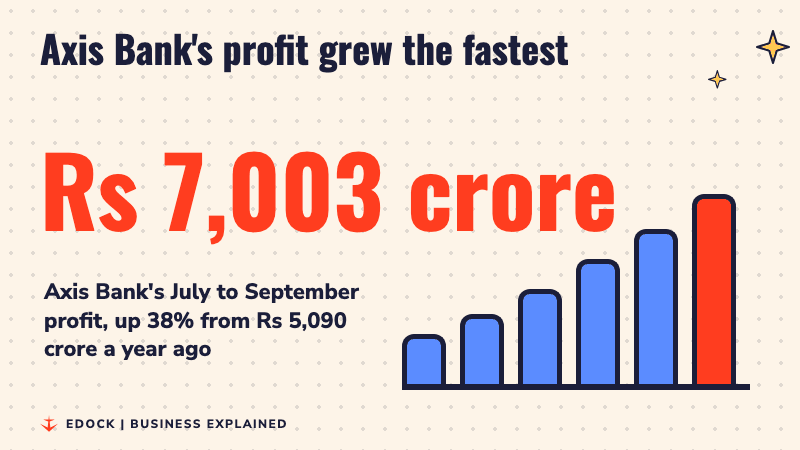
Even so, it was not a perfect score. Analysts had expected about Rs 7,124 crore, so the bank fell a little short. Profit was also 2% lower than in the April to June quarter, Mint reported. Running costs rose 9% to Rs 10,819 crore, partly because the bank spent more on technology and digital services.
Axis also took in more than $10 billion of FCNR deposits. Its NIM slipped to 3.36% from 3.46% in the previous quarter. Chief financial officer Rajeev Mantri put the hit from these deposits at about 11 basis points. A basis point is one hundredth of one percent, so 11 basis points is 0.11 percentage points.
So what does this mean for a young saver?
Banks are lending a lot right now. ICICI's loans grew 30% in a year, and Axis Bank's grew 23%. To lend more, banks need more deposits, which is one reason they went after those dollar deposits.
The bigger lesson is about reading headlines. A bigger profit number does not always mean faster growth. HDFC Bank earned the most money but grew the slowest. Axis Bank earned the least of the three but grew the fastest, mostly because it set aside less for bad loans. Next time you see a result, ask three questions: Did NII grow? Did provisions go up or down? And is the margin getting thicker or thinner?
This post explains the news. It is not advice to buy or sell any share.
Sources
- HDFC Bank Q2 net profit rises 4.7% to Rs 19,510 crore as NII grows, Business Standard
- ICICI Bank Q2 net profit rises 20% to Rs 14,843 crore; NIM slips to 4.18%, The Economic Times
- ICICI Bank Q2 net rises 20% to Rs 14,843 crore as provisions fall, Business Standard
- ICICI Bank sees another margin squeeze in Q3 as FCNR-B costs kick in, Mint
- Axis Bank Q2FY27 result: Profit rises 38% to Rs 7,003 crore, misses estimates, Business Standard
- Axis Bank's rising costs, FCNR inflows squeeze Q2 margins, Mint
- HDFC Bank deputy MD Kaizad Bharucha to step down on December 31, The Economic Times
- Cover photo: Stacks of Coins, by Kevin Schneider, CC0

You may republish this story under CC BY 4.0: credit Pranav Sharma and link to this page.